The papers are signed, the keys are yours, and your camera roll already has a few closing-day photos. Congratulations! Between packing boxes and planning where the furniture will go, it’s easy to put the paperwork aside. But a few simple steps after closing can help you settle in, stay organized, and avoid unnecessary confusion.
Here’s a practical checklist for your next chapter as a Florida homeowner.
1. Give Your Closing Documents a Permanent Home
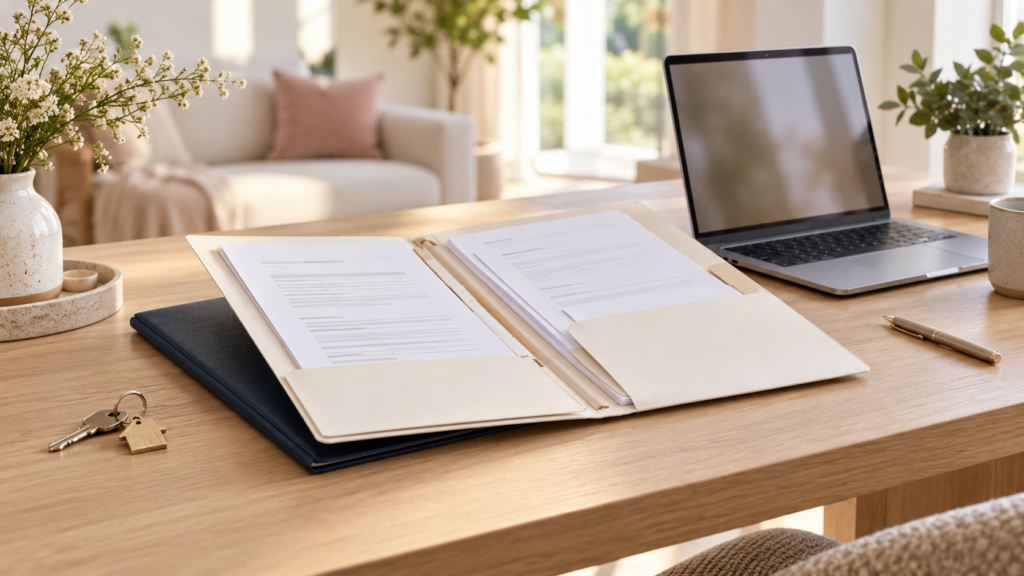
Before the moving boxes take over, create a secure folder for your home purchase records. Keep copies of your final settlement statement or Closing Disclosure, deed, and any mortgage documents that apply to your purchase. Add your homeowners insurance information, survey if provided, and other important property records.
A password-protected digital backup can make these documents easier to find later. You may need them when refinancing, selling, reviewing insurance coverage, or discussing your purchase with a tax professional.
Smart tip: Save your title company’s contact information in the same folder so you know whom to contact if a document is missing.
2. Ask About Your Recorded Deed and Title Insurance Policy
The documents you sign at closing and the final documents you receive afterward may arrive at different times. Ask your closing team how and when you should expect your recorded deed and, if purchased, your owner’s title insurance policy. Delivery methods and processing times can vary.
When you receive them, save them with your closing records. Review your policy and ask questions about anything you do not understand, including its coverage and exceptions. An owner’s title insurance policy and a lender’s policy protect different interests. If you are unsure which policies were issued for your transaction, your title team can help clarify.
3. Confirm Your First Mortgage Payment
If you financed your purchase, make sure you know:
When your first payment is due.
Which company will receive the payment.
How to access your account.
How to set up automatic payments, if desired.
Use your closing documents and verified lender or servicer contact information to confirm the details. If you receive a notice that another company will service your mortgage, read it carefully and verify the payment instructions before making changes.
Smart tip: Add a reminder to your calendar even if you plan to enroll in autopay. Confirm that enrollment is active before relying on it.
4. Get Clear on Taxes, Insurance, and Association Payments
Your mortgage payment may not include every cost associated with your home. Review your documents and ask your lender or servicer which expenses, if any, are paid through your mortgage escrow account. Identify the payments you will need to manage separately.
If your property belongs to a homeowners or condominium association, confirm your account setup, payment schedule, and contact information with the association or its management company.
It is also a good time to contact your county property appraiser’s office about any exemptions you may qualify for, including Florida’s homestead exemption. Confirm eligibility, required documents, and filing deadlines directly with that office. Do not assume that an exemption held by the previous owner automatically applies to you.
5. Update Access to Your Home
Before everyday life gets busy, make a plan for the property’s access points. Consider rekeying or replacing exterior locks and updating garage, gate, alarm, and smart-lock codes. Review who has access through any connected home apps.
Confirm utility transfers and update your mailing address with the organizations that need it.
If the property is in a managed community, ask about mailbox keys, parking permits, gate access, and resident registration. These small tasks can make your first week feel much more settled.
6. Verify Unexpected Mail and Payment Requests
Homeownership often comes with more mail, including advertisements and offers that may look official. Before paying an unexpected charge or sharing personal information, confirm who sent the request and what it is for. Contact the appropriate company or public office using contact details you independently verify.
If a letter concerns your deed, title insurance, or closing paperwork, ask your title company to help you understand it before you act. You do not need to make a payment simply because a notice looks urgent.
7. Keep a Short List of the Right Contacts
When a question comes up, knowing whom to call can save time.
Keep these contacts together:
Title company: Closing records, recorded deed, and title insurance questions.
Mortgage servicer: Payments, account access, and mortgage escrow questions.
Insurance agent: Coverage, policy changes, and claims.
HOA or condominium management: Association payments, access, and community procedures.
County property appraiser: Property information and exemption questions.
You do not have to remember every detail from closing day. You just need to know where to find the information and whom to ask.
Your After-Closing Checklist
Before you put the paperwork away, check these items off:
Save your closing documents securely.
Confirm how you will receive your recorded deed and title policy.
Verify your first mortgage payment details, if applicable.
Identify payments you must handle separately.
Check property tax exemption requirements.
Update locks, access codes, utilities, and your address.
Keep important contacts easy to find.
Frequently Asked Questions About What to Do After Closing
What documents should I keep after closing on a home?
Keep your final Closing Disclosure or settlement statement, deed, mortgage documents if applicable, and any title insurance policies issued for your purchase. Save your homeowners insurance information and survey, if provided, in the same secure folder.
When will I receive my recorded deed and owner’s title insurance policy?
Processing and delivery times vary. Ask your closing team when to expect these documents and whether they will arrive electronically or by mail. Contact them if you have not received the documents within the estimated timeframe.
When is my first mortgage payment due?
Your first payment date appears in your loan documents. Confirm the due date, payment amount, and payment instructions with your lender or mortgage servicer. If you enroll in autopay, verify that it is active before relying on it.
Do I need to apply for Florida’s homestead exemption after buying a home?
If the property will be your permanent residence, you may qualify. An exemption held by the previous owner does not automatically establish your eligibility. Contact your county property appraiser’s office to confirm the requirements, documents, and filing deadlines.
Are property taxes and homeowners insurance included in my mortgage payment?
They may be included if your loan has an escrow account, but you should confirm which expenses it covers with your mortgage servicer. Association dues and other property expenses may require separate payments.
Who should I contact if I have questions after closing?
Contact your title company about closing records, your recorded deed, or title insurance. Your mortgage servicer handles loan payments and mortgage escrow questions, while your insurance agent handles homeowners coverage.
At Smart International Title, we’re happy to help you understand your closing documents and direct you to the appropriate contact when needed.
Have another question? Call 407-854-2115 or visit www.smartinternationaltitle.com.
This article is provided for general educational purposes and is not legal advice. Probate, estate, and Florida homestead matters can vary significantly based on individual circumstances. Consult a qualified Florida attorney for advice regarding a specific estate or legal matter.